Audit-ready grant records allow an independent reviewer to understand what the organization did, why it made each material decision, how it spent the award, and whether the results and costs agree with the governing requirements.
Preparation is not a box-building exercise performed after a notice arrives. It is the routine creation, reconciliation, and preservation of evidence throughout the award. When records follow the transaction and activity, an audit or monitoring review becomes a structured verification process instead of a reconstruction project.
This guide explains how to organize records, build complete audit trails, test internal controls, prepare staff and partners, respond to requests, and turn findings into durable improvements.
Understand the type and scope of review
An external financial audit, single audit, desk review, program monitoring visit, site visit, internal review, and closeout examination may focus on different questions. Read the notice, engagement letter, request list, award terms, and applicable requirements before assembling material.
Identify the award, period, programs, locations, transactions, systems, and objectives in scope. Record the reviewers, authority, schedule, submission method, security requirements, and primary contacts. Ask focused questions when a request is ambiguous rather than sending an uncontrolled data dump.
Create one controlled response process
Name a response coordinator who receives requests, assigns owners, reviews material, tracks delivery, and preserves what was submitted. Establish technical, financial, program, legal, privacy, and executive contacts as appropriate.
Use a request log with item number, wording, owner, source, due date, status, reviewer, delivery date, and follow-up. Save a read-only copy of each response package and transmission confirmation. This prevents conflicting answers and missing versions.
Start with the governing documents
Assemble the signed award, application, approved budget, special conditions, amendments, incorporated regulations, written funder guidance, approved changes, policies, and key correspondence. Build a chronological award history.
When sources appear inconsistent, identify which document controls and obtain qualified guidance. Do not hide amendments in email folders. Reviewers need to see the authority behind a changed budget, schedule, scope, key person, or reporting requirement.
Build transaction-level audit trails
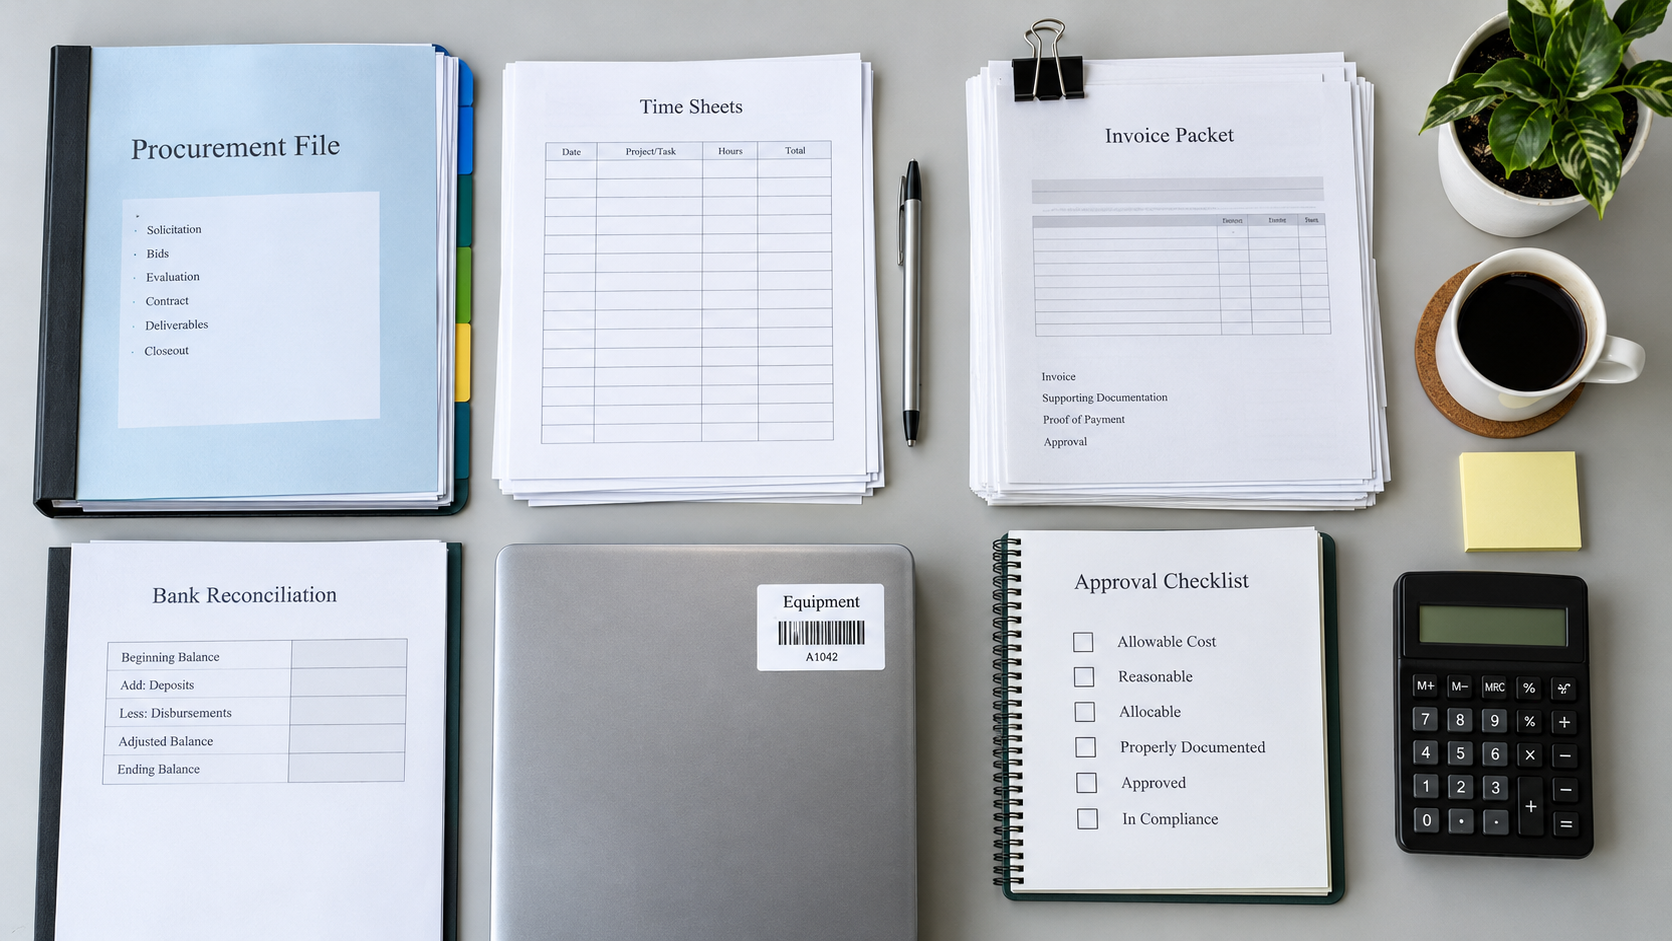
A transaction file should connect the general ledger entry to the underlying need, authorization, procurement or selection, receipt of goods or services, invoice, payment, allocation, and grant purpose. The sequence should show who acted, when, and under what authority.
Support varies by cost type. Payroll may require personnel authorization, pay rate, effort support, payroll register, allocation, and approval. Travel may require purpose, authorization, itinerary, receipts, and reimbursement. Equipment may require competition, invoice, receipt, tag, location, inventory, and disposition controls.
Reconcile the financial story
Reconcile the approved budget, accounting records, reimbursement requests, cash receipts, match, partner invoices, and financial reports. Explain timing differences and corrections. Total expenditures should be reproducible from the ledger and agree with what was reported after documented adjustments.
Test beginning balance, current-period activity, cumulative totals, and remaining funds. Review unusual entries, round-dollar amounts, late postings, negative balances, manual journal entries, and costs near the project boundary. Confirm that corrections preserve an audit trail rather than overwriting history.
Verify allowability and allocation
For sampled costs, document why the expense was necessary for the award, occurred within the allowed period, followed policy, received approval, and was charged in proportion to the benefit received. A receipt proves purchase, not allowability.
Review shared-cost methods for consistency and supporting data. Avoid allocations based only on available budget. If estimates are used temporarily, reconcile them to actual activity under a documented method.
Test payroll and personnel records
Confirm that employees existed, were authorized, worked on relevant activities, received approved compensation, and were charged accurately. Reconcile personnel records, pay rates, payroll, effort support, leave, fringe, and ledger entries.
Protect confidential information and provide only what the review requires through approved channels. Investigate retroactive adjustments, repeated manual changes, unexplained overtime, or allocations that never change despite shifting work.
Review procurement and conflicts
For each selected purchase, show the need, applicable threshold, method, solicitation or quotes, evaluation, conflict disclosure, selection, price analysis, approval, contract, performance, invoice, receipt, and payment.
Explain sole-source or emergency decisions with contemporaneous facts and authority. Verify excluded-party or vendor checks when required. A policy alone is insufficient; reviewers test whether staff followed it.
Examine partner and subrecipient files
Maintain risk assessments, agreements, budgets, flow-down terms, monitoring plans, reports, invoices, supporting samples, communications, corrective actions, and closeout. Confirm whether each relationship was classified correctly.
Reconcile partner-reported costs and performance with the prime recipient’s records. Track unresolved questions. Paying an invoice does not end the prime recipient’s oversight responsibility.
Connect program evidence to reported results
Reviewers may test whether reported outputs and outcomes can be reproduced. Preserve definitions, source systems, eligibility documentation, collection instruments, data cleaning, calculations, exclusions, approvals, and final reported values.
Select several reported figures and trace them back to source records. Then select source records and confirm they appear appropriately in totals. Investigate duplicates, missing periods, inconsistent definitions, and manual changes.
Prepare physical and equipment records
Maintain asset description, serial or identifying number, acquisition date, cost, funding share, location, condition, custodian, use, inventory history, and disposition. Match the register to the ledger and physically verify a sample.
Resolve missing tags, moved equipment, broken items, and disposals before review. Document maintenance, insurance, access, and use when relevant. Confirm restrictions on property acquired with grant funds.
Test internal controls
Walk through how a transaction, participant, report, and change moves through the organization. Identify initiation, authorization, processing, custody, reconciliation, and review. Confirm that roles and system permissions match written policy.
Look for control gaps created by vacancies, remote work, new software, rapid growth, or emergency procedures. Compensating review may be needed in a small organization, but it should be defined and evidenced.
Organize secure electronic records
Use a stable folder structure aligned to the request list and award. Apply consistent file names containing date, category, vendor or subject, and identifier where useful. Separate final records from working copies.
Limit access to sensitive payroll, participant, health, education, or banking information. Use approved secure transfer. Do not email unencrypted personal data merely because a reviewer requested support. Maintain a disclosure log when appropriate.
Conduct a pre-review self-test
Choose a risk-based sample across cost categories, periods, staff, vendors, partners, and locations. Ask someone independent of the original transaction to trace each sample and identify missing evidence, inconsistent treatment, or unclear approval.
Also test nonfinancial requirements: eligibility, service delivery, data, match, acknowledgment, reporting, prior approvals, and special conditions. Document corrective actions, owners, and completion evidence. Do not create backdated records; use a current explanatory memorandum when historical documentation is incomplete.
Prepare staff for interviews and walkthroughs
Tell staff the scope, schedule, coordinator, and their role. Review the actual procedures they perform. Staff should answer truthfully and directly, distinguish fact from memory, and refer questions outside their responsibility to the coordinator.
Do not script misleading answers or guess. If a record is needed, say it will be located. Consistent answers should come from consistent systems, not coaching people to repeat a phrase.
Manage a site visit
Prepare an agenda, workspace, system access, staff availability, safety requirements, participant privacy, and physical records. Verify that observed activities and assets correspond to the award and reported information.
Assign a host who can manage logistics without obstructing review. Record requests and preliminary concerns. Do not stage services or move equipment merely to create an impression; explain normal operations and any current variance.
Respond to questions with complete context
Answer the question asked, identify the source, and explain relevant circumstances. A concise cover note can connect several records in an audit trail. Avoid sending unrelated files that contain sensitive information or introduce confusion.
If an error exists, state it, quantify it, describe the cause, and explain correction. Reviewers generally distinguish an identified and corrected error from concealment or unsupported assertion.
Review findings carefully
For each preliminary finding, confirm the condition, criteria, cause, effect, and questioned amount or risk. Compare it with the record and provide missing evidence or clarification by the deadline. Disagree respectfully with facts and authority, not emotion.
Do not focus only on wording. Determine whether the underlying weakness could recur elsewhere. A narrow sample finding may reveal a broader system issue requiring expanded review.
Create effective corrective actions
A corrective action should address the cause, not merely replace one missing document. Name the action, owner, deadline, resources, affected population of records, verification method, and leadership oversight.
Examples include revising approval workflow, training staff, changing permissions, reconciling additional periods, recovering unsupported costs, monitoring a partner, or adding supervisory review. Retain evidence that the action was implemented and tested.
Distinguish an exception from a pattern
When a sample reveals an error, determine its universe. Search similar transactions, staff, periods, vendors, or data fields. Quantify the potential effect and document the method. A one-time mistake may require correction; a pattern may require repayment, disclosure, process redesign, and broader testing.
Preserve records after the review
Keep the request list, response log, submitted files, interview notes, findings, responses, final report, corrective actions, and closure evidence. Update the award file and risk assessment. Share lessons with relevant teams without exposing confidential information.
A closed review may not end all retention obligations. Litigation, claims, property, unresolved findings, or other rules can extend them. Document the basis for eventual destruction.
Common preparation mistakes
- Waiting for a notice before organizing records.
- Sending files without a controlled response log.
- Treating receipts as complete audit trails.
- Failing to reconcile ledger, reimbursement, and report totals.
- Providing policies without evidence they were followed.
- Backdating missing approvals or recreating records deceptively.
- Ignoring partner and subrecipient documentation.
- Overproducing sensitive or unrelated information.
- Coaching staff to guess instead of answer accurately.
- Correcting the sample without testing the larger population.
Audit-readiness checklist
- Governing award documents and amendments are complete.
- Financial reports reconcile to the accounting system.
- Transactions contain need, approval, support, receipt, payment, and allocation evidence.
- Payroll and effort support agree with personnel and ledger records.
- Procurement files demonstrate the required process.
- Partner classifications, agreements, monitoring, and invoices are documented.
- Reported performance can be reproduced from source data.
- Equipment records agree with physical assets and the ledger.
- System permissions and actual practice support internal controls.
- Sensitive records can be transferred securely.
- Known exceptions have documented corrective actions.
- Staff understand the review process and their responsibilities.
Frequently asked questions
How soon should preparation begin?
Begin at award setup. Create the filing structure, responsibility matrix, reconciliation schedule, and evidence requirements before transactions occur. A formal self-review several months before an expected examination can then test a functioning system.
What if a document is missing?
Search authoritative systems and third parties, document the search, and obtain legitimate replacement evidence when possible. Prepare a current explanation of facts and corrective action. Never backdate or fabricate a record.
Should every transaction be reviewed in advance?
Use controls proportionate to risk and requirements. Routine transactions can follow standard workflow, while unusual, high-dollar, related-party, sole-source, or boundary-period costs may need enhanced review.
Can scanned records replace originals?
That depends on applicable rules and reliable document controls. Ensure scans are complete, legible, protected, retrievable, and linked to the transaction. Preserve originals when required by the award, law, policy, or document type.
What is the difference between an audit and monitoring review?
An audit commonly follows professional standards and tests financial statements, awards, or compliance. Monitoring may focus more directly on program performance, award terms, and corrective support. The actual scope in the notice controls preparation.
Who should speak with reviewers?
The coordinator should route requests, while staff with direct knowledge explain their work. Finance should address accounting, program staff delivery, data staff measures, and leadership governance. One person should not guess across every subject.
What if the organization disagrees with a finding?
Respond within the process using the record, governing criteria, calculation, and a clear explanation. Separate factual disagreement from corrective action the organization can still take. Preserve correspondence and final resolution.
Make every record tell the same story
Create a permanent award index
Maintain an index that lists each record category, responsible owner, system or folder, retention rule, confidentiality level, and backup. Include award terms, amendments, financial records, payroll, procurement, partners, program evidence, data, property, reports, communications, reviews, and closeout.
The index helps a new employee or reviewer locate authoritative records without searching individual accounts. Update it when systems, owners, or requirements change. Test several links and retrieval steps during routine management reviews.
Use a population-and-sample method
Before testing, define the complete population: all transactions, employees, participants, contracts, partners, assets, reports, or changes in the period. Check that the population agrees with control totals. A sample drawn from an incomplete list cannot support a reliable conclusion.
Select items based on both coverage and risk. Include high-dollar, unusual, manual, late, related-party, sole-source, boundary-period, and corrected items, plus ordinary items across the period. Record the selection method so another reviewer can understand the result.
Perform a two-way reporting trace
First select amounts and performance claims from submitted reports and trace them back through calculations to source records. This tests whether reported information is supported. Then select transactions and service records from source systems and trace them forward into reports. This tests whether relevant information was omitted.
Resolve differences in definitions, cutoffs, duplicates, exclusions, and timing. Preserve the reconciliation and final calculation used for each formal report so future staff do not have to recreate it.
Review information-system evidence
When records come from software, document the system, report parameters, extraction date, user, filters, and transformation. Retain the raw export when appropriate and protect it from alteration. Screenshots alone may omit records or settings needed to reproduce a result.
Review access rights, change logs, approval workflows, backups, interfaces, and manual uploads. If totals move between systems, reconcile both sides and investigate rejected or duplicate entries. Explain spreadsheet calculations and protect important formulas.
Prepare a secure review room
For electronic reviews, create a restricted workspace organized by request number. Give reviewers only the necessary access, set an expiration date, and retain an access log when supported. Remove unrelated personal or confidential data from copies when permitted.
For on-site reviews, provide a controlled workspace and a process for checking files in and out. Never leave original records unattended or mix them with reviewer working papers. Keep a duplicate of everything provided.
Validate corrections before claiming completion
Evidence that a policy was rewritten does not prove the problem is fixed. Test a transaction or reporting cycle under the new process. Confirm staff training, system configuration, approval, reconciliation, and supervisory review. Document who validated the change and when.
For broad findings, sample multiple departments or periods after implementation. Continue monitoring until results show the control operates consistently. Report partial progress accurately instead of labeling an unfinished action complete.
Assess fraud and misconduct indicators responsibly
Unusual patterns do not automatically prove misconduct, but they deserve controlled follow-up. Examples include altered support, duplicate payments, undisclosed relationships, shared credentials, split purchases, round-dollar invoices, inconsistent attendance, or resistance to basic documentation.
Follow the organization’s escalation, confidentiality, nonretaliation, legal, and reporting procedures. Preserve evidence and restrict discussion to people with a legitimate role. Do not conduct an improvised investigation that compromises records or fairness.
Turn the review into organizational learning
After closure, identify which records were hardest to retrieve, which definitions caused disagreement, where work depended on one person, and which controls created delay without reducing risk. Assign improvements beyond the sampled award when the same system serves other programs.
Update training, templates, checklists, system permissions, monitoring plans, and award setup. Share practical lessons with program and finance teams. Audit readiness improves when each review strengthens ordinary work rather than producing a temporary cleanup.
Thirty-day preparation sequence
- Days 1–3: confirm scope, team, request log, secure workspace, and communication rules.
- Days 4–8: assemble governing records and reconcile financial and performance control totals.
- Days 9–15: prepare requested populations, select internal samples, and test audit trails.
- Days 16–20: resolve gaps, document current explanations, and complete legitimate corrections.
- Days 21–24: review partners, assets, access, physical operations, and sensitive-data handling.
- Days 25–27: conduct interview practice and an independent quality review of responses.
- Days 28–30: finalize the index, response packages, logistics, open-issue list, and leadership briefing.
Adjust the sequence to the notice and never sacrifice accuracy for speed. If a request cannot be completed by the due date, communicate early and propose a specific delivery schedule.
Example: reconstructing a complete procurement trail
A reviewer selects an equipment purchase from the ledger. The response package begins with the approved project need and budget authority. It then shows the applicable purchasing threshold, solicitation or quotes, evaluator records, conflict disclosure, selection and price reasoning, approval, purchase order, contract terms, invoice, receiving evidence, payment, accounting code, equipment tag, location, and inventory entry.
The documents are arranged in sequence with a short index. If delivery occurred after the invoice, the package explains the payment control and receiving date. If the lowest quote was not selected, the contemporaneous evaluation shows the permitted basis. The ledger amount reconciles to the invoice and payment, while the asset register confirms custody.
This is stronger than sending a receipt and policy. It demonstrates that the organization identified a legitimate need, followed the correct process, received what it purchased, paid the authorized amount, charged the right award, and continues to control the asset.
Example: resolving a performance-data discrepancy
Suppose a quarterly report lists 420 participants while the service system returns 437. The data owner preserves both extracts, confirms their parameters, and identifies seventeen records entered after the reporting cutoff. The organization verifies that the submitted figure was correct for the stated period and documents the cutoff rule.
If the difference instead came from duplicate records, the team would quantify the error, determine which reports were affected, notify the appropriate authority when required, correct the data, and test the larger population. The distinction matters: a timing difference may need explanation, while a duplicate-counting weakness requires corrective action.
Audit readiness exists when the award, work plan, ledger, transaction files, performance data, partner records, reports, and physical observations agree. Reviewers should not need insider knowledge to connect them.
That consistency supports more than compliance. It gives leaders reliable information, helps staff correct problems earlier, protects public and charitable resources, and demonstrates that the organization can be trusted with future awards.
