Winning a grant creates a new set of responsibilities. A post-award grant management plan turns the signed award, approved proposal, and budget into a coordinated system for delivering the work, controlling funds, documenting decisions, and reporting accurately.
Without a shared plan, program staff may follow the proposal while finance follows the award notice, partners rely on old assumptions, and leadership sees problems only when a report is due. Good management keeps those views aligned from kickoff through closeout.
This guide explains how to interpret an award, assign authority, manage scope and finances, monitor performance, maintain records, communicate with the funder, and finish cleanly.
Treat acceptance as an operational decision
Before accepting, compare the final award with the application. Confirm the amount, period, approved scope, cost sharing, payment method, reporting schedule, special conditions, indirect-cost treatment, and restrictions. An award may differ from the request or incorporate documents by reference.
Identify commitments the organization must fund, staff, or administer. Escalate terms that create legal, financial, privacy, technology, or operational concerns. Acceptance should be authorized by the correct person and based on a realistic plan to comply.
Create an award summary
Translate the agreement into a short internal summary. Include the funder and award number, project and budget periods, amount, payment process, match, key contacts, deliverables, reporting dates, restrictions, approval requirements, record-retention period, and closeout obligations.
Link each item to the controlling source. The summary helps staff work quickly, but the signed agreement remains authoritative. Record amendments and updated contacts so the summary does not become an outdated parallel record.
Hold a structured kickoff
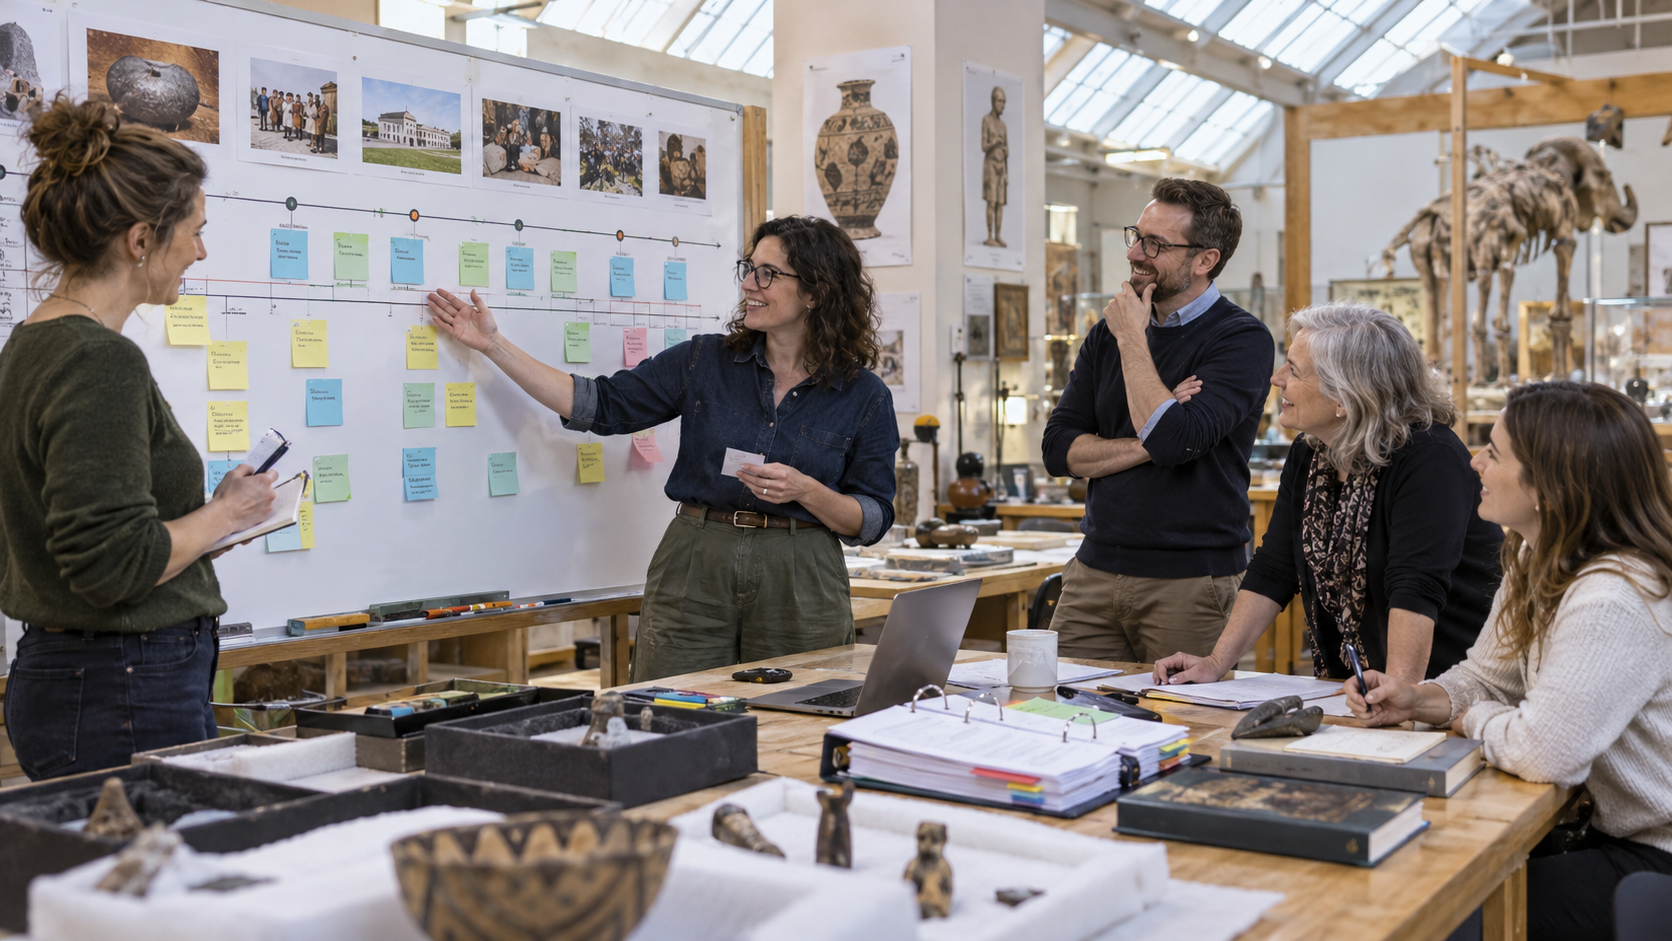
Bring together program, finance, operations, data, development, communications, procurement, human resources, leadership, and relevant partners. Review the project logic, first milestones, budget, reporting obligations, risk areas, and open decisions.
End with named owners, dates, and an issue list. A kickoff is successful when participants understand their responsibilities and dependencies, not when they have merely heard a presentation.
Build a responsibility matrix
For each major task, identify who performs the work, who approves it, who must be consulted, and who needs information. Cover program delivery, participant eligibility, procurement, payroll, budget review, data quality, partner monitoring, communications approval, reporting, amendments, and closeout.
Use roles rather than names in the durable procedure, then maintain a current contact list. Define backup responsibility for critical tasks. Separation of duties should prevent one person from initiating, approving, paying, and reconciling the same transaction.
Convert the proposal into a control plan
Extract every promised activity, output, outcome, partnership, product, and deadline. Place them in a work plan with owners, dependencies, evidence, status, and review dates. Include commitments made in attachments and responses submitted during negotiation.
Distinguish contractual deliverables from internal milestones. Both matter, but missing a funder deadline has different consequences from moving an internal draft date. Keep the plan detailed enough to manage without turning routine work into constant data entry.
Set up the financial structure correctly
Create the grant account, project code, budget, authorized signers, billing method, match tracking, and indirect-cost setup before spending begins. Map the approved budget to the accounting system so reports can be reconciled without manual guesswork.
Document how shared costs, payroll, fringe, travel, procurement, participant support, equipment, and indirect costs will be charged. Confirm allowability before unusual purchases. A budget line does not automatically make a cost allowable, allocable, reasonable, or properly documented.
Establish a monthly financial review
Compare actual spending, commitments, reimbursements, and remaining budget with the work completed and time elapsed. Investigate variances. Low spending may signal delayed hiring or delivery; high spending may reflect accelerated work, coding errors, or an unsustainable pace.
Forecast through the end of the award using known commitments and updated assumptions. Record corrective actions and decisions. Program and finance staff should review the same information together because neither financial nor operational performance tells the full story.
Manage payroll and time support
Document how staff effort is assigned, approved, and reconciled to payroll. Ensure charges reflect work actually performed and comply with the award and organizational policy. Update allocations when responsibilities change rather than waiting for year-end corrections.
Supervisors should understand the project work behind labor charges. Retain required support for salary, fringe, consultant invoices, and contracted labor. Review unusual fluctuations and correct errors promptly with a clear explanation.
Control purchasing and contracting
Apply the required competition, conflict-of-interest, approval, and documentation rules. A complete procurement file should explain the need, method, solicitation or quotes, evaluation, selection, price, approvals, contract, receipt, and payment.
Check whether the award imposes thresholds, domestic preferences, excluded-party checks, or prior approvals. Monitor contractor performance and invoices against deliverables. Do not split purchases or write retrospective justifications to avoid a required process.
Manage partners and subrecipients
Clarify whether another organization is a partner, vendor, contractor, or subrecipient because monitoring responsibilities differ. Use written agreements that define scope, budget, reporting, data, payment, records, communications, intellectual property, and closeout.
Assess risk, review performance, reconcile invoices, and document follow-up. Share relevant award terms and changes. A prime recipient remains responsible for work delegated to others.
Create a documentation architecture
Organize records so another qualified person can reconstruct decisions and transactions. Use consistent folders for award documents, budget, finance, procurement, payroll, partners, program evidence, participants, data, reports, communications, amendments, assets, and closeout.
Set naming conventions, version control, access permissions, backup, and retention rules. Protect sensitive information. Store final signed and submitted records separately from drafts while preserving the evidence needed to explain material changes.
Track performance and evidence together
Define each output and outcome, source, collection method, frequency, owner, quality check, and reporting use. Establish baselines and participant definitions before counting begins. Make sure program systems can produce the totals promised in the proposal.
Pair every milestone with evidence: attendance, completed products, service records, photographs with consent, meeting records, approvals, or data extracts. Evidence should demonstrate what occurred without collecting unnecessary personal information.
Control scope, budget, and schedule changes
Create an issue process that records the condition, effect, options, recommendation, authority, and decision. Determine whether a change is within internal discretion or requires funder approval. Submit requests before implementing changes whenever required.
Do not let small informal adjustments accumulate into a different project. Update the work plan, budget forecast, responsibilities, and evaluation measures after approval. Preserve the request and response with the award records.
Communicate with the funder clearly
Name the authorized contact and route material communications through that role. Ask concise questions, explain relevant context, and retain written responses. When reporting a problem, describe its effect, corrective action, decision needed, and timing.
Do not hide significant delays until a report. Early communication gives the funder more options and demonstrates control. Routine updates should be accurate and proportionate rather than frequent messages with little decision value.
Prepare reports throughout the period
Build report fields into routine data collection and financial review. Maintain a reporting calendar with drafting, data freeze, reconciliation, review, authorization, submission, and confirmation dates.
Reconcile narrative claims, performance tables, and financial figures before submission. Explain variances and corrective actions. Retain the submitted package, attachments, approvals, and confirmation. Never reconstruct the entire reporting period during the final week.
Monitor risk
Maintain a short risk register covering staffing, delivery, participation, data, finance, procurement, partners, technology, safety, reputation, and schedule. Record likelihood, impact, mitigation, trigger, owner, and current status.
Review risks during management meetings and escalate based on defined thresholds. Risk management should lead to decisions, not merely produce a list. Close risks that no longer apply and document new ones as conditions change.
Manage communications and recognition
Confirm requirements for funder acknowledgment, logos, press releases, publications, participant stories, and public data. Obtain approvals and consent before release. Coordinate program accuracy with communications quality.
Avoid claims that exceed verified results or imply funder endorsement. Keep copies of required notices and major public products in the grant file.
Plan closeout from the beginning
Create a closeout checklist early. Include final services, partner deliverables, unpaid obligations, financial reconciliation, final reports, refunds, asset disposition, record retention, data preservation, staff transitions, participant communication, and lessons learned.
Begin well before the project end. A project period ending does not mean all invoices, reports, and administrative obligations disappear that day. Confirm the funder’s deadlines and preserve access to staff and systems needed to finish.
Use a regular management rhythm
- Weekly or biweekly: delivery tasks, near-term milestones, issues, and participant operations.
- Monthly: budget-to-actual, forecast, performance data, partner status, and risk.
- Quarterly: outcomes, scope, sustainability, leadership decisions, and funder reporting readiness.
- Annually or by project period: formal budget revision, performance review, asset verification, policy check, and continuation decision.
Adapt the cadence to the award. Small grants need proportionate controls, but every award benefits from predictable review.
Common post-award mistakes
- Starting work before staff understand the final award terms.
- Managing from the proposal while ignoring special conditions.
- Separating program and financial review.
- Charging costs because budget remains rather than because costs are allowable and necessary.
- Allowing partners to work without current agreements.
- Making material changes before required approval.
- Collecting data that cannot reproduce report totals.
- Keeping key records in personal email or drives.
- Waiting until deadlines to reconcile or report.
- Treating closeout as a final-week task.
Frequently asked questions
Who should own grant management?
One role should coordinate the award, but responsibility is shared. Program owns delivery, finance owns accounting controls, data staff support measurement, operations and procurement support compliant execution, and leadership owns major decisions. Define this explicitly.
How detailed should the plan be?
It should enable a qualified backup to understand obligations, decisions, and current status. Use more detail for high-risk or complex awards and less for routine tasks. Link to procedures instead of copying entire policies.
What if the approved budget does not match actual needs?
Analyze the cause, forecast the effect, and determine whether rebudgeting is allowed or needs approval. Do not move costs silently. Update internal controls and work plans after the decision.
How should underspending be handled?
Investigate whether it reflects delay, savings, vacancies, coding errors, or reduced delivery. Develop a realistic corrective plan. Spending quickly merely to exhaust funds can create unallowable costs and poor results.
When should the funder be contacted?
Follow the agreement and contact the funder early for material scope, budget, schedule, leadership, compliance, or performance concerns. Use the authorized channel and preserve the response.
Can management be handled in a spreadsheet?
A spreadsheet may be sufficient for milestones, budgets, risks, and actions if access, versioning, privacy, and backup are controlled. It does not replace the accounting system, signed records, or required data systems.
How long should records be retained?
Use the award terms, applicable law, and organizational policy. Retention periods can be extended by audits, litigation, property, or unresolved findings. Record the controlling rule instead of assuming one period applies to every award.
Manage the promise, not only the money
Build a first-90-days launch plan
During the first 30 days, finalize acceptance, the award summary, roles, account structure, partner agreements, reporting calendar, data definitions, and immediate approvals. Confirm hiring, procurement, and system-access lead times. Record any condition that could prevent the approved start.
During days 31 through 60, test delivery and documentation workflows. Process an early transaction from request through reconciliation, trace an early participant or service record through the data system, and review the first partner submission. Correct design problems before volume increases.
During days 61 through 90, complete the first integrated management review. Compare milestones, spending, data quality, staffing, risks, and partner performance. Update the forecast and submit any necessary approval requests. The purpose is to prove that the operating system works, not simply that activity has begun.
Maintain a decision log
Material decisions should not disappear into meetings and inboxes. Record the date, issue, facts, alternatives, decision, authority, owner, implementation date, and affected documents. Link to the supporting approval or funder response.
A decision log helps staff understand why a process changed and allows reviewers to distinguish deliberate management from inconsistency. It is especially useful during turnover, when new leaders inherit choices made under earlier conditions.
Design dashboards for action
Choose a small set of indicators that support decisions: enrollment, service completion, outcome progress, spending rate, cash position, vacancies, partner deliverables, data completeness, and upcoming deadlines. Show targets, actual values, trend, owner, and action status.
Do not create a dashboard that merely decorates meetings. Define what variance requires investigation, escalation, or a change request. Preserve the detailed source data behind summaries and document any change in definitions.
Coordinate cash flow and reimbursement
An award can be financially healthy on paper while straining cash if reimbursement is slow. Forecast payroll, vendor payments, partner advances, reimbursement timing, documentation lags, and available working capital. Assign responsibility for claims and follow-up.
Reconcile each request to eligible recorded costs and each receipt to the correct receivable. Avoid drawing funds earlier than permitted or leaving completed claims unsubmitted. Inform leadership before cash pressure affects delivery.
Control participant eligibility and benefits
If the award limits who may receive services or benefits, define required evidence, verification timing, exceptions, privacy, and supervisory review. Train staff to apply criteria consistently and respectfully. Separate eligibility determination from performance reporting when that reduces error.
For stipends, incentives, scholarships, or participant support, document authorization, recipient, purpose, amount, receipt, and any required tax or consent process. Reconcile distributions to inventory, payment systems, and reported participation.
Manage data privacy and access
Collect only information needed for delivery, reporting, evaluation, or compliance. Document legal and contractual requirements, consent, data sharing, retention, deletion, breach response, and restrictions on publication. Review partner and vendor access.
Use role-based permissions and remove access promptly after staff transitions. Avoid emailing sensitive exports or storing them in personal accounts. Test backup and recovery, not merely the existence of backup settings.
Prepare for turnover
For every critical role, maintain current procedures, calendars, credentials under organizational control, contact lists, open issues, and near-term deadlines. Assign a backup and conduct periodic handoffs. No award should depend on one person’s memory.
When turnover occurs, reconcile responsibilities and system permissions immediately. Notify the funder when required, update signature and contact authority, and review whether the staffing change affects scope, schedule, or budget.
Use a proportionate review calendar
Not every control needs the same frequency. High-volume transactions may be sampled monthly, equipment verified periodically, system permissions reviewed quarterly, and policies confirmed annually. Increase review when risk rises, a new process begins, or errors appear.
Document the calendar, reviewer, sample method, result, and follow-up. Repeated review without recorded action offers little protection. Conversely, excessive approval layers can delay service without improving control.
Questions for quarterly leadership review
- Are activities and outcomes progressing together?
- Does the forecast support completion within the period?
- Are material variances understood and assigned?
- Have any award terms, personnel, partners, or assumptions changed?
- Can reported figures be reproduced?
- Are cash flow and match sufficient?
- Which risks require executive or board action?
- Which approvals must be requested now?
- What evidence should be shared with the funder?
- What must happen before the next review?
Example: managing a delayed project launch
Imagine that a two-year workforce grant requires three training cohorts, but the lead instructor resigns during the first month. The program team records the vacancy and its effect on recruitment, delivery, spending, and outcomes. Finance updates the forecast rather than assuming the delayed salary will automatically fund another purpose.
The manager reviews the award to determine whether a replacement, schedule change, or budget shift requires approval. Leadership compares options: hire permanently, contract temporarily, move the first cohort, or reduce scope. The team selects a temporary instructor while recruiting, documents qualifications and procurement, and asks the funder to approve a revised first-cohort date.
After approval, the work plan, forecast, risk register, participant communications, partner calendar, data schedule, and reporting narrative are updated. The next monthly review checks whether recruitment and spending are recovering. This approach treats delay as a managed change with connected operational and financial effects, rather than allowing separate teams to improvise conflicting fixes.
Minimum records for every management meeting
Keep the current work plan, budget-to-actual report, forecast, performance dashboard, risk and issue log, decision log, partner status, upcoming approvals, and reporting calendar together. Record decisions and owners before the meeting closes. The package should show the same reporting cutoff and version date.
This discipline creates a continuous management record and reduces the effort required for reports, turnover, audits, and closeout. It also lets leadership see whether an apparently isolated problem affects other commitments.
Post-award management protects the relationship between resources, activities, evidence, and results. Financial compliance matters, but a perfectly coded ledger cannot compensate for missed services or unsupported outcomes.
A practical plan gives the team one view of obligations, authority, performance, finances, risks, and decisions. With that foundation, the organization can solve problems earlier, report confidently, and close the award with a record that withstands review.
